


I opened a position in Acciona Energía ($ANE) on September 28 at 22.73 euros, in the aftermath of a week in which the market had become nervous about the possibility that the government might reinstate the Iberian exception. It’s a purchase I’d had in mind since the summer, when serious talk began about the sale of the renewable energy subsidiary, and it was precisely that regulatory buzz that made me pull the trigger. I believe the market is conflating two things that don’t carry the same weight: a political threat that I see as very difficult to carry out, and a corporate process that, if it goes through, has a target price significantly higher than the current one.
| POST FROM SEPT. 28 | TARGET PRICE | ACCIONA'S PARTICIPATION | INSTALLED CAPACITY |
| 22.73 EUR | 28 EUR | 91,1% | 14,699 MW |
Before getting into the thesis: The Scenario Framework
As I always do when I open a position with a certain degree of conviction, I start by writing down the range of possible outcomes I foresee. In the case of Acciona Energía, this range depends on two nearly binary variables—the sale process and regulation—and a third, more gradual factor: the price of electricity in Spain.
| Scenario | Target Price | Potential | Key Assumptions |
|---|---|---|---|
| Pessimistic | 18.5 EUR | -19% | Either Acciona decides not to sell, or the offers fall short of its asking price; the government reinstates some form of intervention in the wholesale price, and the stock returns to the area of its annual lows |
| Home | 28 EUR | +23% | My valuation is based on the sum of its parts. It aligns with the range within which I believe a takeover deal will be finalized, with a mandatory tender offer to minority shareholders at the same price. |
| Optimistic | 30 EUR | +32% | A real competition between EQT and Norges on one side and Ardian on the other, with year-end debt already below 3,000 million |
Entry price: 22.73 euros, September 28, 2026. Our own target prices. The consensus among the 21 analysts covering the stock is 23.15 euros, with a high of 28.10 and a low of 17.
I am aware that my base-case scenario is practically at the upper end of the consensus range. I’ll explain this further below, but here’s a preview: most analysts value Acciona Energía as a publicly traded company with a 9% free float and zero liquidity, while I’m valuing it as what I believe it is right now—an asset for sale.
What Acciona Energía Is Today: A platform with a capacity of nearly 15 GW that the market has failed to recognize
Acciona Energía went public in July 2021 at 26.73 euros per share. Five years later, it is trading 15% below that price, even though the company’s scope of operations is significantly larger than it was then. As of the end of June, it had 14,699 MW of installed capacity, distributed mainly among onshore wind, solar, and a hydro portfolio in Spain that, in my view, is among the most undervalued assets in the entire sector. Consolidated production for the first half of the year was 12,535 GWh, a 4% increase from a year earlier.
Acciona Energía’s problem on the stock market has never been its assets; it has been its structure. With Acciona controlling 91.1% of the capital, the free float is barely 9%; liquidity is very low, and a large portion of institutional investors simply cannot make significant investments. Added to this was a very difficult cycle for publicly traded renewable energy companies: high interest rates that make financing more expensive, depressed prices in Spain during peak hours, and asset turnover that makes quarterly profits dependent on when a sale is finalized. The result is a company that the stock market has been valuing at a discount to the value of its generation fleet for the past three years.
The Semester's Numbers, A Closer Look
At first glance, the first half of 2026 was a bad one. Revenue of 1.288 million, down 12%; EBITDA of 388 million, down 57%; and an attributable net loss of 18 million. If you just look at the headline, it’s easy to see why the stock hasn’t taken off.
But you have to read the fine print. The drop in EBITDA is almost entirely due to the timing of asset turnover: last year, capital gains from sales occurred in the first half of the year, while this year they were realized in July. The company itself has kept its 2026 guidance unchanged: total EBITDA of about 1.2 billion, investment of 900 million, and net debt below 3.0 billion at year-end. That last figure is the one that interests me the most. As of June 30, net financial debt stood at 4,442 million, so management is saying it will reduce it by more than 1,400 million in six months, with the two July sales already closed and more than 1 GW additional in the rotation portfolio.
The other key factor is price. Electricity futures in Spain for the second half of the year are trading above 100 euros per MWh, a far cry from the prices we’ve seen in recent springs. Forecast production in Spain has been cut from 8.5 to 8 TWh due to lower resource availability, but at those prices, the second half of the year should be significantly better than the first.
Why I bought it: The asset is for sale, and the asking price is not 22 euros
Here lies the crux of the matter. Acciona has spent months analyzing strategic alternatives for its renewable energy subsidiary, ranging from bringing in a minority partner to selling a controlling stake or divesting entirely. That process accelerated in September. On September 15, it was reported that EQT, through its infrastructure division, has partnered with Norges Bank Investment Management—the manager of Norway’s sovereign wealth fund—to submit a joint bid for 100% of Acciona Energía. EQT would hold approximately 75% of the consortium, with Norges holding the remaining 25%. Ardian is the competing bidder. The enterprise value reported in the press is around 11.9 billion, including debt, and final bids are expected by mid-October, when Acciona will select a candidate for exclusive negotiations.
There are three aspects of this process that I think are very important and that I believe the market is not factoring into prices.
The first is who is bidding. These aren’t opportunistic funds looking for a bargain; they are two of Europe’s largest infrastructure investors and a sovereign wealth fund with one of the lowest costs of capital in the world. When Norges sits down at the table, it does so because it wants long-term assets with predictable cash flows and is willing to pay for them. And when two consortia of that size are competing, the seller holds all the cards.
The second issue is the mechanics of the tender offer. If the buyer gains control of Acciona Energía, Spanish regulations require it to launch a tender offer for the remaining shares at a fair price, which cannot be lower than the price it paid to Acciona. Put another way: a minority shareholder buying today at 22 or 23 euros would receive the same price per share as Entrecanales. It is one of the few situations on the stock market in which the minority shareholder is aligned with the majority seller, and the majority seller has every incentive in the world to secure the highest possible price.
The third is the benchmark of 26.73 euros. That was the initial public offering price, and even before there was any talk of a sale, most analysts were already treating it as the reasonable floor for a hypothetical delisting takeover bid by Acciona itself. I find it very hard to imagine Acciona’s board selling its renewable energy crown jewel to a fund for less than the price at which it was taken public five years ago. For the sake of reputation and simple arithmetic, I believe the negotiations will start at that figure—not end at it.
Why EVs on the Road Fall Short
The reported enterprise value of 11.9 billion is calculated, as far as I can tell, based on the debt figures as of June. And the debt that Acciona will transfer to the buyer will not be the same as it was in June. If the company meets its guidance and ends the year with debt below 3,000 million, we’re talking about more than 1,400 million less in debt. With 329.25 million shares outstanding, every 1,000 millones of debt that is eliminated represents approximately 3 euros per share in value for shareholders, assuming the same enterprise value. That is, to a large extent, the difference between the price the market is paying today and the price at which I believe the transaction will close.
My Model: The Sum of Parts by Technology
To arrive at the figure of 28 euros, I did not want to rely on the consensus or on multiples from publicly traded companies, because the market has been applying a discount to the sector for years that is not seen in private transactions. I have constructed a simple sum-of-the-parts valuation, valuing each installed megawatt based on its technology, using private market benchmarks and being deliberately conservative with wind power, which makes up the bulk of the portfolio.
| Technology | Approximate Capacity | Value per MW | Estimated Value |
|---|---|---|---|
| Onshore Wind Power | 9.4 GW | 0.95 million euros | 8,930 M€ |
| Photovoltaics | 4.2 GW | 0.60 M€ | 2,520 M€ |
| Hydraulics (Spain) | 0.9 GW | 1.80 M€ | 1,620 M€ |
| Other (biomass, solar thermal, storage, services, portfolio under development) | 0.2 GW | - | 550 million euros |
| Enterprise Value | 14.7 GW | 13,620 M€ | |
| Pro forma net debt after rotations | -3,100 M€ | ||
| Minority Interests and Other Adjustments | -1,300 M€ | ||
| Equity Value | 9,220 M€ | ||
| Per share (329.25 million shares) | 28,0 € |
Approximate breakdown of capacity and values per MW of self-generated power. Net debt is slightly above the year-end guidance for prudence.
Some comments on the assumptions. At 0.95 million per MW, I’m valuing wind power below what it costs today to build a new onshore wind farm in Europe—and that’s even though a significant portion of Acciona’s portfolio consists of sites with excellent resource potential and, in Spain, grid connections that are nearly impossible to obtain today. I’m setting solar PV at 0.60, in line with replacement cost and without a premium. Hydropower is where I see the most hidden value: these are manageable assets, with long-term concessions and the ability to generate power precisely during the hours when solar power drops out of the system—which are precisely the peak-demand hours. In a market with an increasing share of solar power, a hydropower plant becomes more valuable with each passing year.
The resulting enterprise value—approximately 13.6 billion—amounts to about 0.93 million per installed MW and just under 13 times normalized recurring EBITDA, which I estimate at about 1.05 billion. I do not consider this a demanding multiple for a platform of this size, with geographic diversification and a buyer who will finance the transaction at infrastructure cost.
The most significant sensitivity is that of wind power: every 0.10 million per MW up or down moves the valuation by about 2.85 euros per share. If someone wants to be more conservative than I am and lower the wind power valuation to 0.85, the result is a value of around 25 euros, which is still 10% above my entry price. To justify the 22.73 euros at which I bought, I would have to value wind power at around 0.77 million per MW—a level I don’t see in any recent transactions.
The Iberian Exception: Why I Don't Think It's Feasible
On September 17, CCOO and UGT proposed to the government that the Iberian exception be reinstated, and a few days later, Yolanda Díaz included it in her package of proposals along with rent caps and a tax on refining. The market reacted as expected: Grenergy fell 13.5% in a single trading session, Solaria nearly 6%, and Acciona Energía just under 2%. I made my purchase during those days, and I want to explain why I believe that fear is overblown.
Let’s recall how the mechanism worked. Between June 2022 and December 2023, a cap was placed on the price of gas used to generate electricity—initially set at 40 euros per MWh and then rising to 70—and consumers paid the difference through an adjustment on their bills. The effect was to lower the wholesale price and, with it, the revenue from all non-gas-fired technologies: nuclear, hydroelectric, and renewables. It is estimated that these technologies lost up to 6 billion euros in revenue.
In my opinion, repeating that today is not feasible, for four reasons.
The first is that the mechanism no longer serves its intended purpose. In 2022, gas set the price at around 75% per hour. Today, it hovers around 15%. Capping gas prices when gas is almost never the marginal technology has very little effect on the average bill, and the political and legal costs of implementing it remain the same. If the goal is to lower inflation, it is a very ineffective tool.
The second is Brussels. The 2022 Iberian exception was approved as exceptional state aid, in the wake of the invasion of Ukraine and within a crisis timeframe that no longer exists. Since then, the reform of the European electricity market has established a specific procedure for this type of intervention: it must be the Council that declares a price crisis at the regional or Union level, and for that to happen, wholesale prices must be 2.5 times the average of the previous five years and exceed 180 euros per MWh, with the expectation that they will remain at that level for months. With futures around 100 euros, we’re nowhere near that threshold. And the message coming out of Brussels is that there is no appetite for reopening that debate.
The third is that there is no single voice within the government itself. The proposal comes from the Sumar faction and the unions. From the Ministry of Economy, Carlos Cuerpo has spoken of measures to support families, which is very different from intervening in the wholesale market. The electricity industry association has already stated publicly that the conditions for reviving the market do not exist. And I cannot imagine the government intervening in electricity prices while two of the world’s largest infrastructure investors are about to sign a deal worth nearly 12,000 million for a Spanish company. The message to foreign investors in the sector would be devastating, just when Spain needs to attract tens of billions for grid expansion and energy storage.
The fourth point pertains specifically to Acciona Energía. A very significant portion of its production in Spain is covered by bilateral contracts and fixed-price PPAs, and another substantial portion of its generation takes place outside of Spain. Sabadell’s own analysts have been saying this recently: a new Iberian exception would have less impact than it did in 2022, and for companies with most of their production under contract, the effect would be limited. It makes sense that Grenergy or Solaria, which are more exposed to the spot market, would suffer more. For Acciona Energía, a drop to 2% already seems like a good entry price to me.
I’m not saying that regulatory risk in Spain is zero—it never is in this sector. What I am saying is that the likelihood of the Iberian exception returning in its 2022 form is low, and that even if a watered-down version were approved, the impact on Acciona Energía’s valuation would be in cents, not euros.
Technical Analysis: A Year of Range-Bound Trading and a Narrowing Price Range
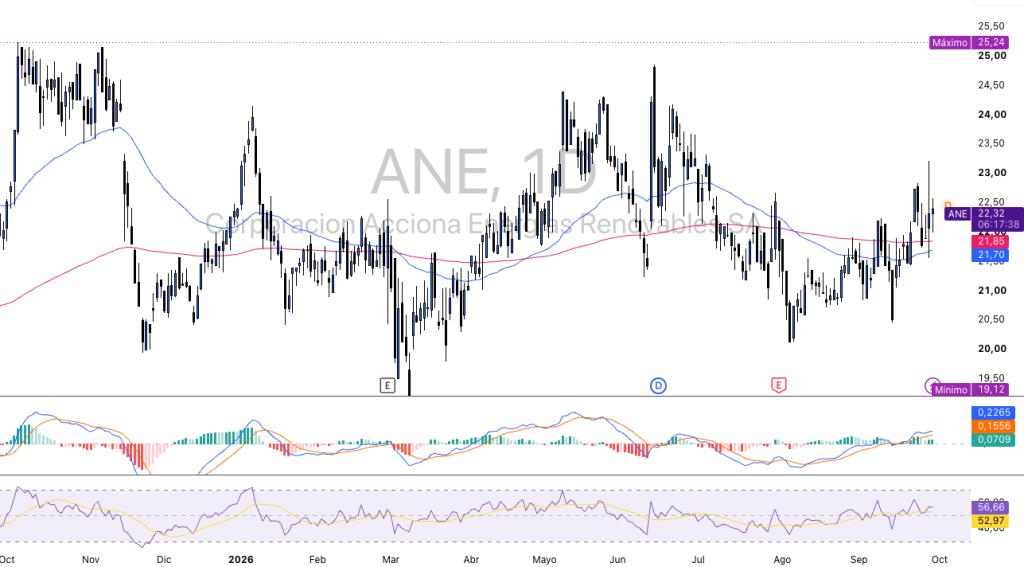
Looking at the one-year daily chart, the first thing you notice is that Acciona Energía isn’t trending—it’s ranging. Since October 2025, the price has fluctuated between the high of 25.24 euros reached in the fall and the low of 19.12 euros recorded in early March, with three complete swings between those two extremes. This is the typical chart for a stock with no free float, where the price is driven by news rather than a steady flow of buying.
The interesting part lies within that range. The lows are getting higher: 19.12 in March, 20.14 on August 6, and 20.46 on September 14. And the highs are getting lower and lower: 25.24 in the fall, 24.86 on June 15, and 23.22 during the session when I entered the trade. The price is being squeezed, and when such a squeeze coincides with a time-sensitive catalyst—such as the binding offers in mid-October—the breakout is usually violent in one direction or the other.
If I look at the last six months, the picture is more favorable. After reaching a high in June, the stock corrected throughout July and much of August until it found support at 20.14 euros. From there, it formed a double bottom: on September 14, it fell another 3.93% to 20.52 euros, with an intraday low of 20.46, and did not break below the August support level. The next day, news broke about EQT and Norges, and the stock rose 4.48% to 21.44.
Last week was the litmus test. On September 22, it closed at 22.74 euros, up 3.36%, and over the next three days, amid all the buzz surrounding the Iberian exception, it gave back part of that gain, falling to 21.78 on September 24—a closing price that fell right between the 50-session exponential moving average (21.63) and the 200-session exponential moving average (21.84). The price did not fall any further. On Monday, the 28th—the day I entered the position—the trading session sums it all up: it opened at 22.08, hit a low of 21.56 (below both moving averages), reached a high of 23.22, and closed at 22.32, with a gain of 1.92% and a volume of 489,280 shares—more than double the usual volume in previous sessions, which had ranged between 100,000 and 280,000 shares. I bought at 22.73 within that range. The upper wick up to 23.22 tells me there are sellers there, and the lower wick down to 21.56 tells me that below the moving averages, someone is willing to buy in large quantities.
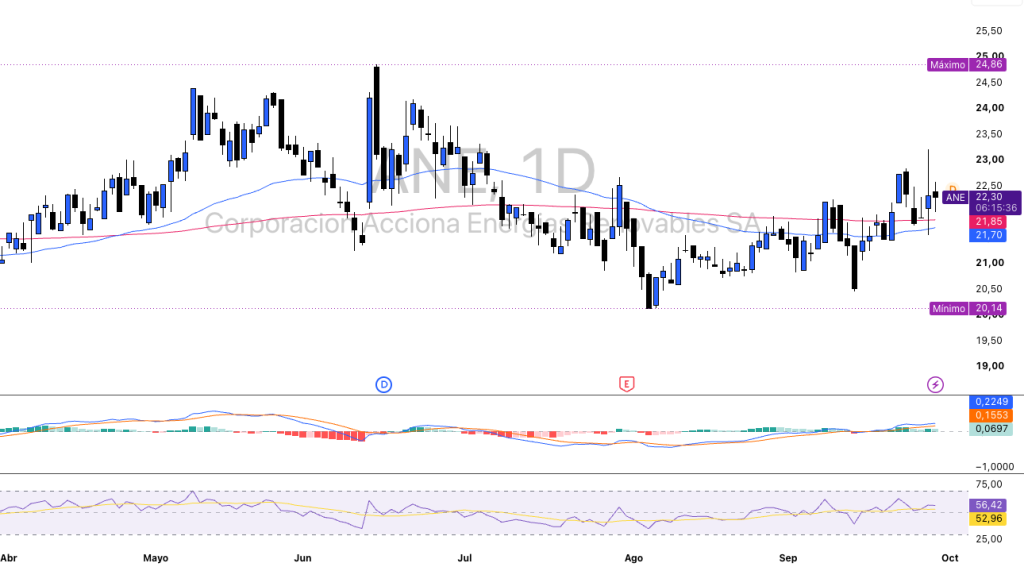
If I look at the last six months, the picture is more favorable. After reaching a high in June, the stock corrected throughout July and much of August until it found support at 20.14 euros. From there, it formed a double bottom: on September 14, it fell another 3.93% to 20.52 euros, with an intraday low of 20.46, and did not break below the August support level. The next day, news broke about EQT and Norges, and the stock rose 4.48% to 21.44.
Last week was the litmus test. On September 22, it closed at 22.74 euros, up 3.36%, and over the next three days, amid all the buzz surrounding the Iberian exception, it gave back part of that gain, falling to 21.78 on September 24—a closing price that fell right between the 50-session exponential moving average (21.63) and the 200-session exponential moving average (21.84). The price did not fall any further. On Monday, the 28th—the day I entered the position—the trading session sums it all up: it opened at 22.08, hit a low of 21.56 (below both moving averages), reached a high of 23.22, and closed at 22.32, with a gain of 1.92% and a volume of 489,280 shares—more than double the usual volume in previous sessions, which had ranged between 100,000 and 280,000 shares. I bought at 22.73 within that range. The upper wick up to 23.22 tells me there are sellers there, and the lower wick down to 21.56 tells me that below the moving averages, someone is willing to buy in large quantities.
Moving averages are about to give a signal not seen since the summer. The 50-session EMA stands at 21.70 euros and the 200-session EMA at 21.85. The 50-session EMA crossed below the 200-session EMA in early August, when both were around 22.02 euros, and since then it has been closing the gap: on September 14, it stood at 21.53, and now it’s just 15 cents away from the 200-session EMA. If the price stays above 22 euros for a few more trading sessions, the bullish crossover will happen in a matter of days. On its own, this isn’t a signal that would prompt me to buy, but it confirms that the summer correction is now behind us.
The indicators are in line with this trend. The MACD crossed the zero line between September 14 and 18, when it moved from -0.03 to +0.04, and at the close of trading on the 28th, the main line stood at 0.2265 compared to 0.1556 for the signal line, with the histogram in positive territory (0.0709). The 14-session RSI closed at 56.66 on the 28th, above its average of 52.97. It peaked at 62.58 on September 22 and has since corrected without approaching overbought territory. It had come from 39.34 on the 14th, so in two weeks it has moved from a zone of weakness to a zone of moderate strength, with plenty of room to run before reaching 70.
The price levels break down as follows. On the upside, the first resistance level lies between 23.22 euros—the high from the 28th—and 23.66 euros—the quarterly high. A close above that zone with high volume would break the series of lower highs and pave the way toward the June high of 24.86 and the annual high of 25.24. Above 25 euros, the chart becomes irrelevant, and the price will be driven by corporate news. On the downside, the 21.70 to 21.85 zone—where the two moving averages lie—is the first support level, and the true support lies at 20.14 to 20.46, the double bottom from August and September. My bearish scenario, at 18.50, is deliberately set below the annual low of 19.12, because breaking below that level on heavy volume would signal that the sell-off has gone off the rails.
| Level | Reference |
|---|---|
| 30,00 € | Optimistic goal |
| 28,00 € | Basic Objective |
| 26,73 € | Initial Public Offering Price (2021) |
| 25,24 € | Maximum of 52 weeks |
| 24,86 € | High on June 15 |
| 23.22 – 23.66 € | Immediate Resistance |
| 22,73 € | Admission price |
| 21.70 – 21.85 € | 50-day EMA and 200-day EMA |
| €20.14 – €20.46 | Double Bottom in August and September |
| 19,12 € | At least 52 weeks |
Target price and catalysts: 28 euros, with upside potential to 30
My target price is 28 euros. That’s what my sum-of-the-parts analysis yields; it’s above the IPO price, and it’s consistent with the range within which I believe Acciona will want to close the deal. If the bidding war between EQT, Norges, and Ardian heats up, I see room for the final offer to reach the 30-euro range, especially if the buyer values the hydropower portfolio and the debt—which has already been reduced—at year-end. I wouldn’t dare go above that, because we’d start paying multiples that not even a sovereign wealth fund could easily justify.
Mid-October 2026. Final bids.
Acciona will select a candidate to negotiate exclusively with. This is the main catalyst for the thesis.
October and November. Third-quarter results.
First reading with prices above 100 euros and July's inventory turnover already reflected in the accounts. We'll see how much the debt has actually decreased.
In progress. Debate on the Iberian exception.
Every week that passes without a concrete draft, and with Brussels remaining unchanged, is a week in which the market will gradually phase out the regulatory risk premium.
End of the year. Debt below 3 billion.
If the guidelines are followed, the implied value per share in any offer rises almost automatically.
Thesis Risks: What Can Go Wrong
Let there be no operation.
That is the main risk. Acciona may decide that the offers do not meet its expectations, or it may choose to bring in a minority partner without relinquishing control, which would not trigger a takeover bid for the publicly traded shares. In that case, the stock would return to trading as it has in recent years—an illiquid, discounted security—and likely in the range of 19 or 20 euros.
Let the regulation take us by surprise.
Although I don't see it as a viable option, intervention in the wholesale price—even if only partial—would affect the portion of Spanish production that is not covered and would dampen buyers' enthusiasm.
Electricity Rates.
The valuation of any renewable energy source ultimately depends on the price it commands. If futures prices above 100 euros turn out to be a mirage and we return to situations like those in the spring, with zero prices during daylight hours, the value-per-MW assumptions will suffer.
Interest Rates and Liquidity.
A rise in long-term interest rates makes financing more expensive for buyers and can put downward pressure on the asking price. And with a floating ratio of 9%, any movement—in either direction—is amplified.
Abstract: Asymmetry with a Date
I’ll summarize the thesis as I see it. I’ve purchased a platform with a capacity of nearly 15 GW at 22.73 euros—a platform the market has been discounting for years due to its ownership structure—just as that structure is about to disappear. The controlling shareholder has put the asset up for sale; there are at least two top-tier consortia competing for it—one of which includes the Norwegian sovereign wealth fund—and regulations require that minority shareholders receive the same price as the majority shareholder. My sum-of-the-parts valuation brings me to 28 euros without the need for overly optimistic assumptions, and the IPO price of 26.73 serves as a benchmark that’s very hard for the seller to ignore.
I’m facing a real corporate risk—that the deal might not close—and regulatory noise that the market has amplified more than I think it warrants. The Iberian exception belongs to a different era of the electricity market, and both the figures and the current European framework make it very difficult to replicate.
The asymmetry lies in the relationship between those two sides. I’m betting on around 19% in the adverse scenario to aim for 23% in the central scenario and 32% if bidding heats up. And unlike other investment theses where you have to wait years for the results to show up on the bottom line, here the catalyst has a set date: in a few weeks, we’ll know who will be sitting down for exclusive negotiations and within what price range.
 Spanish
 English
 German
 French
Goal11Login is super easy to use, even for a beginner like me. The interface is clean and straightforward. I definitely recommend it if you're just starting out. goal11login